Globus Power Generation Limited has approved a proposal to acquire a 51% stake in Transtech Punjab CBG LLP for a cash consideration of up to ₹65 lakh, marking a planned expansion into India’s compressed biogas (CBG) sector.
The transaction involves acquiring the partnership interest held by Amitabh Tandon, a partner in Transtech Punjab CBG LLP and a Non-Executive Director at Globus Power. The company has classified the proposed acquisition as a related-party transaction and stated that it is being conducted on an arm’s length basis.
Completion remains subject to shareholder approval, according to the supplied announcement. The company has also stated that no government or regulatory approvals are required for the specific investment.
The acquisition would give Globus Power a majority interest in an entity engaged in producing compressed biogas and fermented organic manure, two products associated with the conversion of organic materials into energy and agricultural inputs.
Transtech Punjab CBG LLP was incorporated in April 2024 with an initial capital contribution of ₹10 lakh. Its capital contribution was subsequently increased to ₹1 crore in October 2025, according to the supplied source material.
The entity’s reported turnover increased substantially between the two financial years presented.
Related-party transaction requires shareholder approval
The proposed acquisition is a related-party transaction because the seller, Amitabh Tandon, holds positions in both the target LLP and Globus Power.
The company has stated that the transaction is being undertaken on an arm’s length basis. The acquisition will be funded through cash consideration of up to ₹65 lakh, with completion conditional on shareholder approval.
The proposed transaction should not yet be described as a completed acquisition. Shareholder approval and subsequent completion remain outstanding conditions in the supplied announcement.
What the acquisition could mean for Globus Power
The investment would provide Globus Power with a majority partnership interest in a business focused on compressed biogas and fermented organic manure. This would broaden its exposure to the bioenergy sector and potentially give it access to an operating business rather than requiring it to develop a new venture from the beginning.
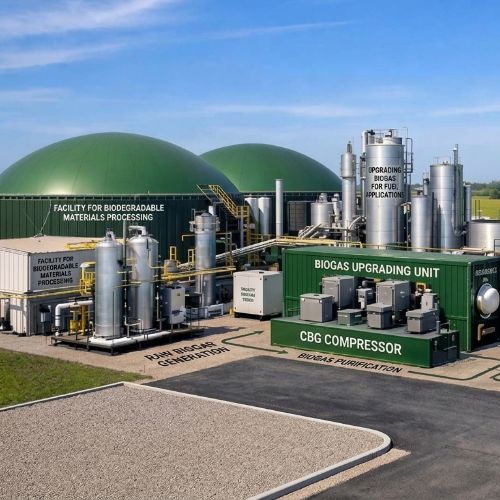
CBG is produced by upgrading biogas generated from biodegradable materials. Depending on the feedstock and process configuration, these materials can include agricultural residues, organic municipal waste and other biodegradable resources. Fermented organic manure is a potential agricultural co-product of anaerobic digestion.
However, the announcement does not establish the target’s installed production capacity, the feedstocks it uses, its plant location beyond the available corporate information, or whether it has secured long-term CBG offtake arrangements. Those details will be important for assessing the operational and commercial significance of the investment.
The increase in turnover from FY2024–25 to FY2025–26 is notable, but additional financial information is needed to determine whether the business is generating sustainable earnings and cash flow.
Revenue growth does not establish the acquisition valuation
The proposed consideration of up to ₹65 lakh is substantially smaller than Transtech Punjab CBG LLP’s reported FY2025–26 turnover of ₹5.32 crore. However, comparing the purchase consideration directly with annual turnover is not sufficient to conclude that the target is undervalued.
The consideration is for a 51% partnership interest, not necessarily the entire business. A proper valuation assessment would need to consider the target’s debt and other liabilities, assets, operating margins, capital expenditure requirements, cash flows and the rights attached to the acquired partnership interest.
The financial disclosures supplied with the announcement do not provide enough information to calculate a reliable enterprise valuation or earnings multiple.
For investors, the more relevant questions are whether the target’s revenue growth is supported by sustained CBG production, whether the business is profitable, and what obligations or additional capital requirements Globus Power may assume after acquiring control.
Bioenergy Business Analysis
Globus Power’s proposed acquisition of a 51% stake in Transtech Punjab CBG LLP represents a potential diversification move into India’s compressed biogas market. Rather than announcing a greenfield project, the company is seeking a controlling interest in an existing entity that has reported a substantial increase in turnover during its first two financial years.
The target’s reported revenue growth is noteworthy, but turnover should not be confused with profitability or operating scale. Without information on production capacity, feedstock availability, operating margins, debt and cash flow, it is not yet possible to determine how much commercial value the acquisition could create.
The related-party nature of the transaction also warrants attention. Although Globus Power has stated that the deal is being conducted on an arm’s length basis, shareholder approval and transparent disclosure of the transaction terms remain important safeguards. Investors will also need to understand the target’s financial position and any additional funding required to expand its operations.
For the wider CBG sector, the proposed deal illustrates one route through which companies can enter renewable gas production: acquiring an interest in an existing business rather than building a facility independently. Whether this approach offers a meaningful advantage will depend on the target’s operational performance, the terms of the acquisition and the acquirer’s ability to support the business.
The next milestones are shareholder approval, completion of the transaction and further disclosures about the target’s operating assets and financial performance. Until those details become available, the acquisition is best viewed as a proposed strategic entry into bioenergy rather than evidence of a proven financial or operational turnaround.