
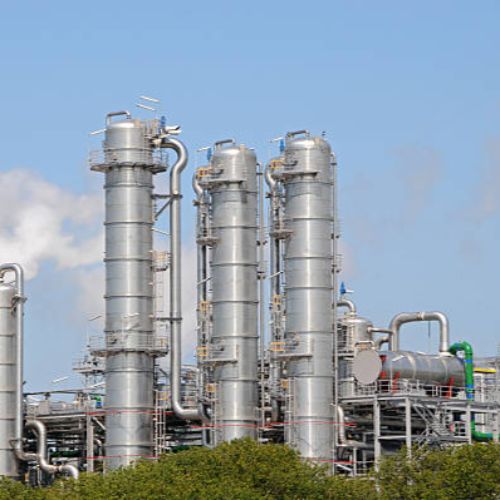
Ukraine has amended the rules used to determine the maximum equipment capacity of ethanol and bioethanol production plants, introducing provisions that allow the actual capacity of production equipment to be considered in the relevant calculations.
The Cabinet of Ministers adopted the changes on 23 September, according to the Ministry of Agrarian Policy and Food. The revised procedure will be used in calculations related to the guaranteed tax liability for excise tax.
New rules address actual production capacity
The updated procedure establishes how changes to the maximum capacity of ethanol and bioethanol production equipment should be identified and sets out a mechanism for recalculating capacity when relevant changes occur.
It also introduces permissible deviations between the actual and maximum capacity of technological equipment. Under the amended rules, actual capacity may differ from the maximum capacity by up to and including 3%.
The provision recognises differences that can arise from the technological characteristics of ethanol production as well as the properties of measuring equipment.
Equipment cleaning provisions clarified
Ukraine’s government has also clarified how coefficients associated with the washing and disinfection of production equipment should be applied.
The amended procedure takes into account that washing and disinfection can take place during scheduled production shutdowns. This provides a specific treatment for equipment downtime within the capacity calculation methodology.
The changes therefore cover both the measurement of production capacity and the operational circumstances that can affect how equipment capacity is calculated.
Impact on excise tax calculations
The revised capacity methodology is directly linked to Ukraine’s excise-tax framework for ethanol and bioethanol production.
The government said the amended rules will be applied when determining the guaranteed tax liability for excise tax. The supplied source does not provide further details on how the change will affect individual producers’ tax liabilities or government excise-tax revenues.
For ethanol and bioethanol producers, the treatment of actual equipment capacity, permitted deviations and scheduled shutdown activities could therefore become relevant to the calculation of their applicable tax obligations.
Bioenergy Business Analysis
Ukraine’s revision brings greater specificity to how production capacity is measured for ethanol and bioethanol facilities in the context of excise taxation. The explicit allowance for a deviation of up to 3% and clarification of cleaning and disinfection periods address operational factors that can affect capacity calculations.
The significance for producers will depend on how the revised methodology is applied in individual facilities and how the capacity calculation translates into guaranteed excise-tax liabilities. The supplied information does not quantify the financial effect of the changes on producers or the wider bioethanol market.
The immediate regulatory development is the adoption of the amended calculation procedure on 23 September, with the revised methodology to be used for guaranteed excise-tax liability calculations.